Featured · · 2 min read
Lower Interest Rate Doesn’t Always Mean a Better Home Loan (Singapore 2026 Guide)
For most homeowners, choosing a home loan feels simple:
👉 “Just pick the lowest rate.”
And in this case, it looks obvious:
- 2-year fixed: 1.45%
- 5-year fixed: 1.88%
Why pay more?
That’s exactly what most people think.
And that’s exactly how they lose money.
The “Obvious” Choice
At surface level, the lower rate wins.
👉 Here’s what it looks like in numbers:
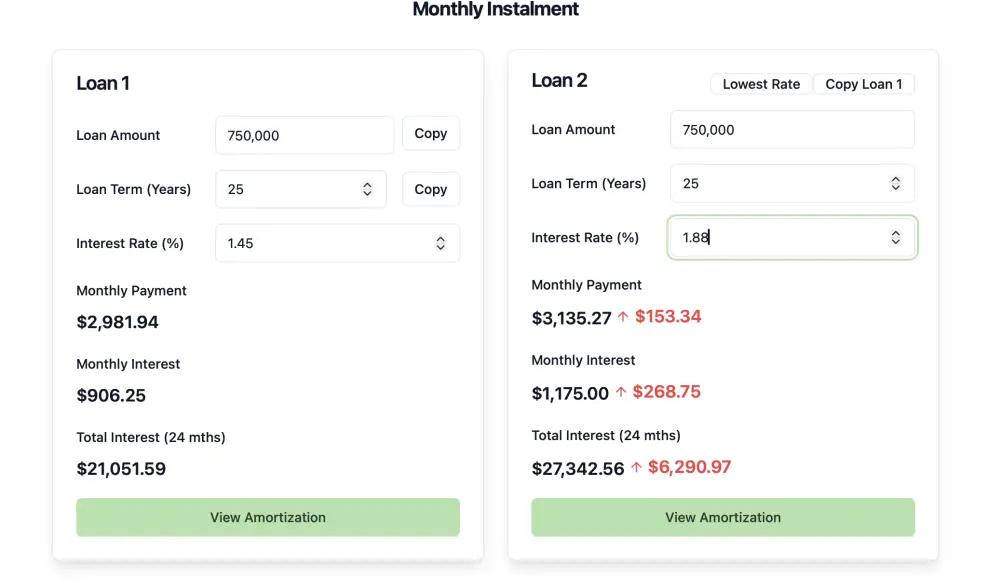
You save about $6K+ in the first 2 years
That’s where most people stop thinking.
The Context That Changes Everything
This is an HDB flat.
👉 Which means:
- Minimum Occupation Period (MOP) = 5 years
If you take a 2-year fixed loan:
- You enjoy low rates for 2 years
- Then you are forced to refinance for the remaining 3 years
You are not choosing a 2-year loan.
👉 You are choosing:
2 years fixed + 3 years UNKNOWN
The Risk Most People Ignore
No one can predict rates.
But we know this:
- Rates were ~1% during COVID
- Rates hit ~3.5–3.7% in 2023
- Long-term range: ~2%–2.5%
Today’s rates (~1.4%–1.9%) are not high.
So the real question is:
👉 What happens if rates go UP when you refinance?
When the “Cheap” Loan Becomes Expensive
Let’s say rates go back to ~3%.
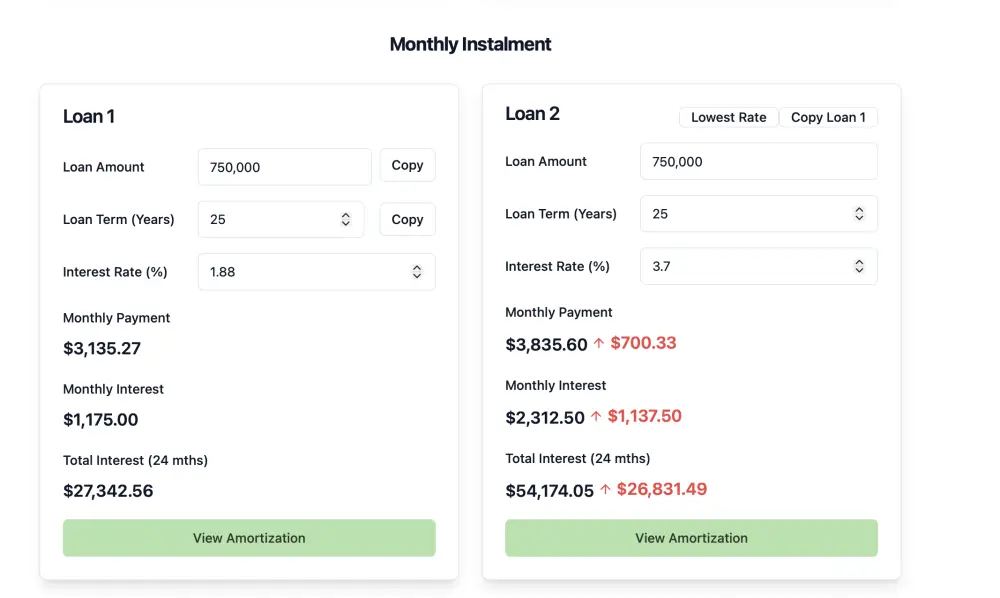
Now look at the impact:
- Monthly jumps by ~$700
- Interest cost explodes
👉 That wipes out your earlier “savings” completely
Even a Moderate Increase Hurts
Let’s be conservative.
What if rates only go to ~2.5%?
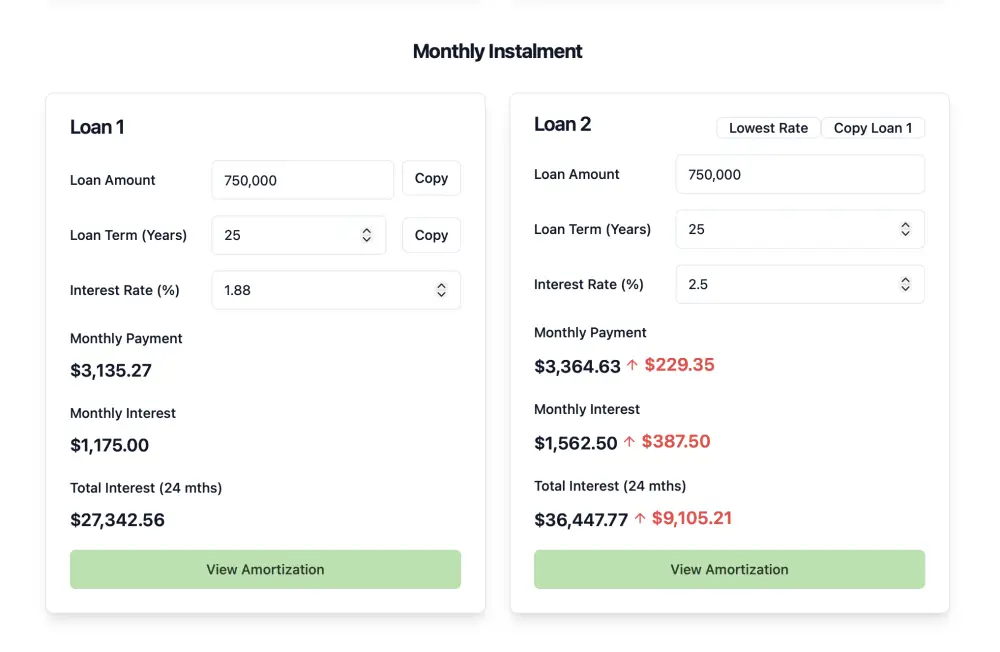
👉 You still lose the advantage.
This is the key point most people miss:
You don’t need a worst-case scenario to lose money.
A normal market is enough.
What You’re Really Choosing
The decision is NOT:
❌ 1.45% vs 1.88%
The real decision is:
👉 Short-term savings vs long-term certainty
Who Should Choose What
Choose 2-year fixed if:
- You believe rates will stay low or drop
- You’re comfortable taking risk
- You want to optimise short-term cost
Choose 5-year fixed if:
- You want stability across MOP
- You don’t want to refinance risk
- You value predictability over optimisation
The Brutal Truth
Lower rate doesn’t mean better.
It just means:
👉 You’re taking on risk (whether you realise it or not)
If you’re not sure which structure fits your situation:
📩 Reach out for a loan review
We’ll break down:
- What actually makes sense
- What risks you’re taking
- What to do next
No fluff. Just numbers.
Written by Loan Experts. General information, not personal advice.